Financial Planning for Senior Living: A Guide for the 2027 Homebuyer
10 October 2026
The year 2027 might feel distant, but if you are a homeowner in your late 50s or 60s, it is practically tomorrow. The decisions you make about housing over the next 24 to 36 months will shape your financial life for the next two or three decades. This is not just about where you will live. It is about how you will fund the life you want when you are no longer working full time.
Most articles about senior living focus on the mechanics of selling a house or the basics of a reverse mortgage. That approach misses the point. The real challenge is sequencing. You have a collection of assets, a set of income streams, and a series of risks. The goal is to arrange them in a way that supports your dignity, your independence, and your budget. This guide is for the person who plans to buy a home in 2027, whether that is a smaller place, a home near family, or a property in a retirement community. We will look at the numbers, the trade-offs, and the mistakes that trip up even smart, experienced homeowners.
Why 2027 Is a Unique Planning Horizon
Planning for 2027 is different from planning for 2035. You are close enough to retirement that the broad strokes of your financial life are already set. You likely know the approximate value of your current home. You have a sense of your Social Security benefits. You may have a 401(k), an IRA, or a pension. You are not guessing anymore. You are optimizing.But you are also far enough away that you still have time to make meaningful changes. You can adjust your savings rate. You can decide to pay down a mortgage. You can investigate long-term care insurance. You can sell a business or a rental property. The window is open, but it is not wide.
The real estate market in 2027 is an unknown, but your personal timeline is not. If you plan to buy in 2027, you will likely be navigating a market that has its own rhythm. Interest rates may be higher or lower than today. Inventory may be tight or abundant. You cannot control that. What you can control is your readiness. That means understanding your cash flow, your tax situation, and your tolerance for risk.
The Three Pillars of Senior Housing Finance
Every senior living decision rests on three pillars: income, assets, and expenses. Most people focus on assets. They know their home is worth a certain amount. They know their retirement account balance. But income and expenses are where the real action is. A large asset base can be misleading if your monthly income does not cover your monthly bills.Income: Beyond Social Security
Social Security is the foundation for most retirees. But it is rarely enough to cover a mortgage, property taxes, insurance, utilities, and daily living. You need other income. That could be a pension, an annuity, rental income, or withdrawals from retirement accounts.The key question is how much of that income is guaranteed. Social Security and pensions are guaranteed for life. Annuities can be structured to provide guaranteed income. Retirement account withdrawals are not guaranteed. They depend on market performance. If you are buying a home in 2027, you should think about how much of your housing cost will be covered by guaranteed income. If the answer is less than 100 percent, you need a plan for the gap.
Assets: The Role of Home Equity
For many seniors, the home is the largest asset. In 2027, you may be sitting on significant equity. That equity can be used in several ways. You can sell the home and use the proceeds to buy a smaller place with cash. You can take out a mortgage on the new home and preserve cash for other uses. You can use a reverse mortgage if you are 62 or older. Or you can keep the home as a rental property.Each option has trade-offs. Paying cash for a new home reduces your monthly expenses, but it also ties up a large portion of your net worth in an illiquid asset. Taking out a mortgage keeps cash available, but it adds a monthly payment and interest cost. A reverse mortgage can eliminate a monthly payment, but it comes with closing costs and a declining equity stake.
Expenses: The Hidden Costs of Senior Living
Most people underestimate the cost of senior living. They think about the mortgage or the rent. They forget about property taxes, homeowners insurance, maintenance, utilities, and health care. They also forget about the cost of aging in place. If you plan to stay in your home, you may need to modify it for accessibility. That could mean a ramp, a stairlift, a walk-in tub, or a first-floor bedroom. Those modifications can cost thousands of dollars.If you plan to move to a retirement community, you need to understand the fee structure. Some communities charge a large upfront entrance fee plus a monthly fee. Others charge a monthly rental fee with no upfront cost. The upfront fee model can be a good deal if you live long enough, but it can be a bad deal if you move out after a few years. You need to run the numbers for your specific situation.
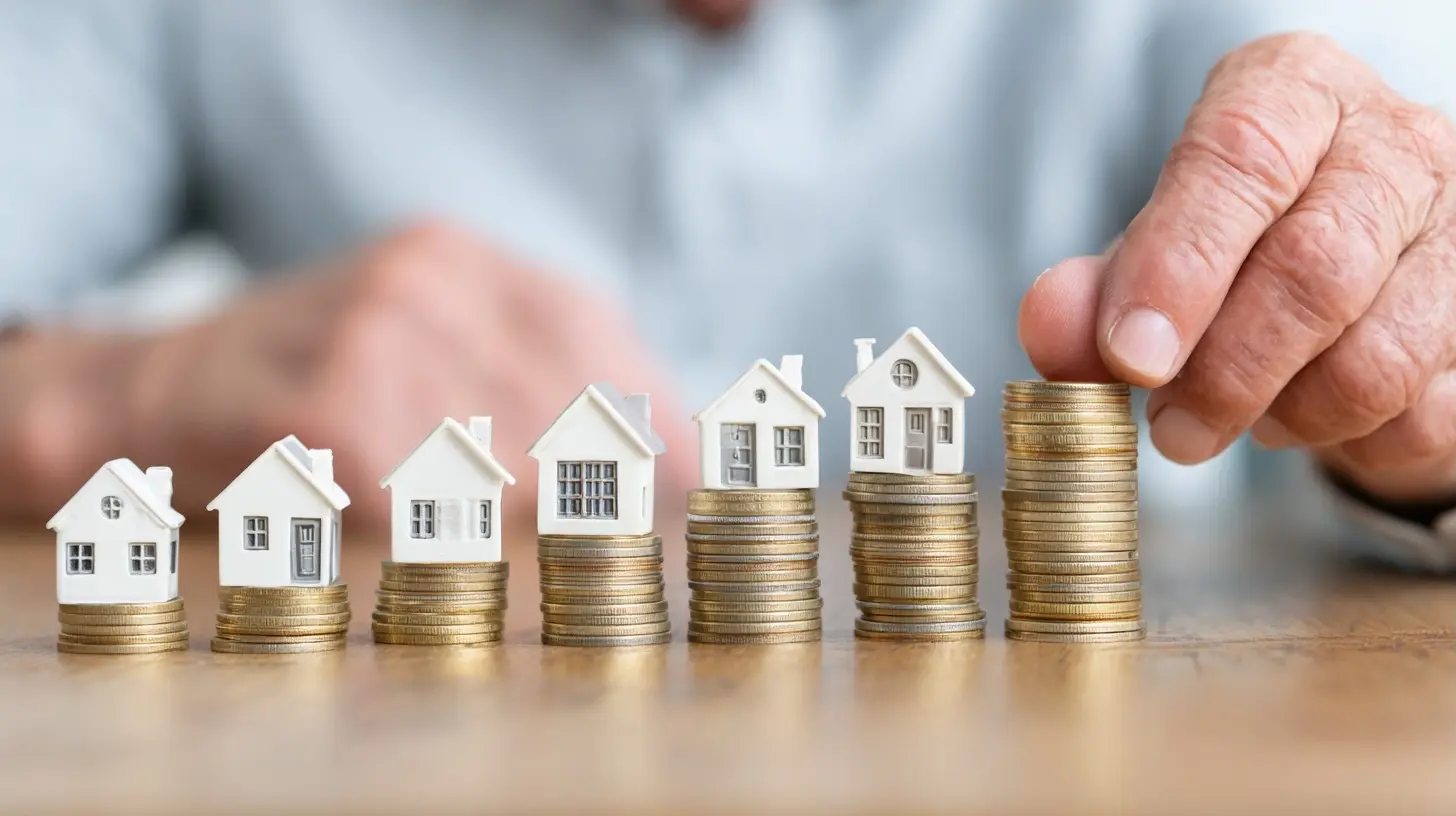
The Buy-Down Decision: Should You Pay Cash or Take a Mortgage?
This is the central question for most 2027 homebuyers. You have equity from your current home. You can use it to buy the next home outright. Or you can take out a mortgage and invest the difference.The answer depends on three factors: your risk tolerance, your tax situation, and your cash flow needs.
If you pay cash, you eliminate a monthly mortgage payment. That improves your cash flow and reduces your stress. But you also lose liquidity. If you need a large sum for a medical emergency or a family need, you may have to sell the home or take out a loan. You also lose the potential investment returns you could have earned on the cash.
If you take out a mortgage, you keep your cash invested. If your investments earn more than the mortgage interest rate, you come out ahead. But that is not guaranteed. The stock market can go down. The mortgage interest rate is fixed. You are taking on sequence-of-returns risk. If the market drops early in your retirement, you could be forced to sell investments at a loss to make the mortgage payment.
A balanced approach is often best. You could pay off a large portion of the home with cash and take out a small mortgage. That keeps your monthly payment low while preserving some liquidity. For example, if you buy a $400,000 home, you could put $300,000 down and take a $100,000 mortgage. The payment on a 15-year loan at a reasonable rate would be manageable. You would still have $100,000 or more in cash for emergencies.
The 2027 Tax Landscape for Seniors
Taxes are a major factor in senior housing decisions. The Tax Cuts and Jobs Act provisions that affect individual taxpayers are scheduled to expire after 2025. That means the tax rules in 2027 could be different from today. You should not assume the current rules will apply. You should plan for the possibility of higher tax rates.For homeowners, the key tax issues are the capital gains exclusion, the mortgage interest deduction, and the property tax deduction.
The capital gains exclusion allows a single filer to exclude up to $250,000 of gain on the sale of a primary residence, and a married couple filing jointly to exclude up to $500,000. You must have lived in the home for two of the last five years. If you are planning to sell in 2027, you likely meet that test. But if you have a large gain, you should calculate your potential tax liability.
The mortgage interest deduction is available on loans up to $750,000 for married couples filing jointly, or $375,000 for single filers. If you take out a small mortgage, you may not itemize deductions. The standard deduction for seniors is relatively high. You should compare your itemized deductions to the standard deduction before assuming the mortgage interest helps you.
The property tax deduction is capped at $10,000 for state and local taxes, including property taxes. If you live in a high-tax state, you may hit that cap. That reduces the tax benefit of an expensive home.
Health Care and Long-Term Care: The Wild Card
Health care is the biggest wild card in senior financial planning. Medicare covers many things, but it does not cover long-term care. That means nursing home care, assisted living, and in-home care are largely out of pocket. The cost can be staggering. A private room in a nursing home can cost over $100,000 per year in many parts of the country. Assisted living can cost $50,000 to $70,000 per year.If you are buying a home in 2027, you need to think about how you would pay for long-term care if you needed it. Some people buy long-term care insurance. Others set aside a portion of their assets for that purpose. Some rely on Medicaid, but Medicaid has strict asset and income limits. You generally have to spend down your assets to qualify.
The location of your new home matters here. Some states have better Medicaid programs than others. Some have more affordable care options. If you are moving to be near family, you should check the local care infrastructure. Are there good assisted living facilities? Is there a strong home health care agency? These are not pleasant questions, but they are necessary.
Renting vs. Buying in 2027: A Real Comparison
Many seniors assume they should buy because they have always owned. But renting can be a better option in some cases. Renting eliminates maintenance costs, property taxes, and the risk of a large repair bill. It also provides flexibility. If your health changes, you can move more easily.The trade-off is that rent can increase over time. A fixed-rate mortgage payment stays the same. If you plan to stay in the home for many years, buying can provide more stability. If you plan to move again in a few years, renting may be cheaper.
Let us run a simple example. Suppose you are looking at a $350,000 home. If you buy with cash, you tie up $350,000. You also pay property taxes of $4,000 per year, insurance of $1,500, and maintenance of $3,000. That is $8,500 per year in carrying costs, plus the opportunity cost of the $350,000. If you could earn 4 percent on that money, that is $14,000 per year. Your total cost of ownership is $22,500 per year, or $1,875 per month.
Now suppose you rent a comparable place for $1,800 per month. That is $21,600 per year. The rent is slightly cheaper. But the rent can go up. The ownership costs are more predictable. Over a 10-year horizon, the owner might come out ahead if home values appreciate. The renter might come out ahead if they invest the difference and the market does well. There is no universal right answer. It depends on your time horizon, your risk tolerance, and your local market.
The Role of a Reverse Mortgage in 2027
A reverse mortgage is a loan that allows homeowners 62 and older to convert part of their home equity into cash. The loan does not have to be repaid until the borrower moves out, sells the home, or dies. The interest and fees are added to the loan balance over time.A reverse mortgage can be a useful tool for some seniors. It can eliminate a monthly mortgage payment and provide a line of credit for emergencies. But it is not right for everyone. The fees are high. The loan balance grows over time. The borrower is still responsible for property taxes, insurance, and maintenance. If those are not paid, the loan can go into default.
If you are buying a home in 2027 and you are 62 or older, you could use a reverse mortgage to buy the home. This is called a HECM for Purchase. It allows you to buy a home with a reverse mortgage and no monthly mortgage payment. You still need to pay property taxes and insurance. The down payment requirement is significant. You generally need to put down 40 to 60 percent of the purchase price. This can be a good option if you want to preserve cash and eliminate a monthly payment. But you should compare it to a traditional mortgage and a cash purchase before deciding.
Common Mistakes to Avoid
The most common mistake is waiting too long to plan. Many seniors start thinking about their housing options only after a health crisis or a financial shock. By then, their options are limited. If you are planning for 2027, you have time. Use it.Another mistake is underestimating the cost of aging in place. Modifying a home for accessibility can be expensive. So can in-home care. If you plan to stay in your home, you should budget for those costs.
A third mistake is assuming you will be able to sell your home quickly when you need to. In a slow market, it can take months to sell. If you need to move for health reasons, that delay can be a problem. You should have a contingency plan.
A fourth mistake is ignoring the tax implications of your decisions. Selling a home with a large gain can trigger a capital gains tax. Taking withdrawals from a traditional IRA can increase your taxable income and affect your Medicare premiums. You should work with a tax professional to understand the full picture.
Building Your 2027 Plan
A good plan starts with a clear picture of your current financial situation. List your assets, your income sources, and your expenses. Then project them forward to 2027. Be realistic. Assume some inflation. Assume some market volatility. Assume some unexpected expenses.Next, define your goals. Do you want to stay in your current area? Do you want to move near family? Do you want to downsize? Do you want to be in a community with amenities and services? Your goals will drive your housing choice.
Then, run the numbers for each option. Compare the total cost of ownership to the total cost of renting. Compare the cash flow impact of paying cash versus taking a mortgage. Compare the tax implications of each choice. Do not rely on rules of thumb. Your situation is specific.
Finally, review your plan with a team of professionals. That should include a financial advisor, a tax professional, and a real estate agent who understands the senior market. A good team can help you avoid mistakes and identify opportunities you might have missed.
Conclusion
Financial planning for senior living is not about picking the perfect investment or the perfect home. It is about aligning your resources with your values. It is about creating a plan that allows you to live with dignity and independence, whatever the future holds. The 2027 homebuyer has time to get this right. Use that time wisely. Start today. Your future self will thank you.
all images in this post were generated using AI tools
Category:
Retirement HomesAuthor:
Elsa McLaurin